VAT · Company Vehicles
Company Cars and Input VAT: The Personal-Use Test
Last reviewed by the Exiloz tax team against the UAE legislation in force on that date. Tax law moves — confirm any figure against tax.gov.ae before you act on it.
Availability, not use, decides the VAT
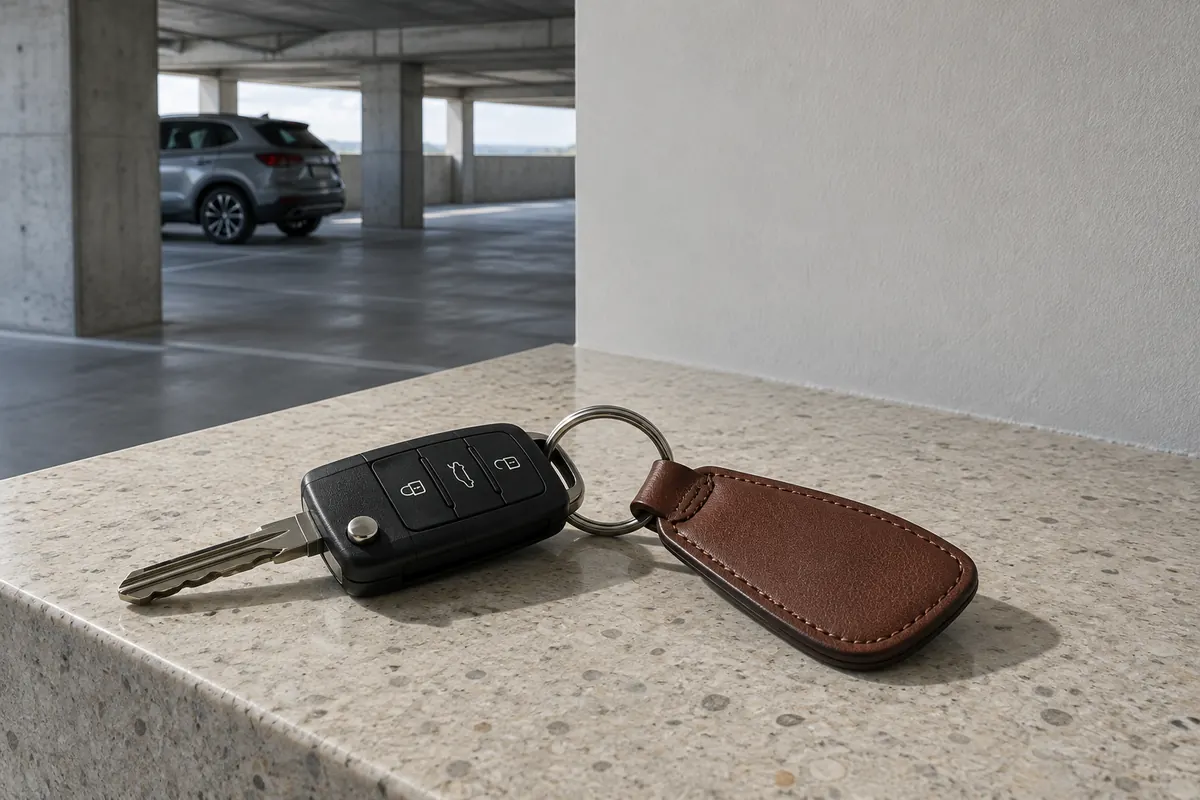
Article 53 of the UAE VAT Executive Regulation blocks input VAT on vehicles available for personal use by anyone. The word that matters is available, not used. A car the sales manager drives home every night is available for personal use, even if every trip is for work. VAT advice on company vehicles starts by sorting the fleet on that test.
Company cars are a common finding in VAT reviews because the amounts are large and the error repeats. Each purchase carries a large VAT amount, and leases repeat the same wrongly claimed VAT every month. This guide covers the rule, which vehicles usually qualify, leases, the resale position and car allowances. It relies on the consolidated VAT Executive Regulation.
Can a UAE company recover VAT on a company car?
Only if the car is not available for personal use by any person. Article 53(1)(b) blocks input tax on motor vehicles bought, rented or leased for the business when that condition applies. Ownership of the car is not the test.
It does not matter that the company owns the car or that most journeys are for work. An FTA auditor may simply ask where the car is parked at night and who holds the keys. If the honest answer is a manager's home, the VAT on it was never recoverable.
Quick Answer
UAE input VAT on a company car is blocked when the car is available for personal use by any person. Company ownership and mostly-business journeys do not change that result.
Which company vehicles usually qualify for VAT recovery?
Commercial vehicles used only for the business, such as delivery vans and trucks. Pool cars can also qualify when they are genuinely not available for private use. SUVs and saloons allocated to named staff usually do not qualify.
Take an illustrative company buying a manager's SUV with AED 7,500 of VAT and a van with AED 6,000. A logged pool car adds AED 4,500, so it recovers AED 10,500 and blocks AED 7,500. Claiming all AED 18,000 would over-claim AED 7,500, which must then be corrected in the next return.
Quick Answer
Delivery vans, trucks and properly controlled pool cars usually qualify for UAE input VAT recovery. Company cars allocated to staff who take them home at night usually do not qualify.
What evidence supports a pool car claim?
A written policy that bans private use of the car, backed by real, enforced controls. Keys should stay at the office outside working hours. A booking log and mileage records should show who used each car and why.
A policy that nobody enforces does not help, and neither does a log filled in once a year from memory. The same test applies to leased and rented cars, so each monthly lease payment on an available car carries blocked VAT. Short business rentals, returned afterwards and documented, are easier to defend.
Quick Answer
UAE pool cars qualify for input VAT recovery only with an enforced no-private-use policy. Keep keys at the office, plus a booking log and mileage records for each pool car.
What happens when a car with blocked VAT is sold?
Article 29 of the VAT Executive Regulation lets the business account for VAT on the profit margin. That applies to goods on which input tax was not recovered under Article 53. The scheme's conditions, including the records it requires, must be met at the time of sale.
Take an illustrative SUV bought for AED 150,000 and sold three years later for AED 70,000. There is no profit margin, so no VAT is due on the margin at all. Charged on the full price instead, VAT would have been AED 3,500.
Quick Answer
A UAE car whose input VAT was blocked can be resold under the profit margin scheme in Article 29. VAT then applies only to any margin, not the full price.
Is a car allowance better than a company car for VAT?
It removes the question, because the company then has no vehicle VAT to claim or block. The employee buys or leases the car personally, and the allowance forms part of pay. For Corporate Tax, the allowance is a staff cost.
It is not always cheaper, since a company car can be bought at fleet prices and resold. Blocked VAT on a company car is not lost for Corporate Tax, because it becomes part of the car's cost and is depreciated. Our note on Corporate Tax and depreciation covers that side.
Quick Answer
A UAE car allowance removes the company vehicle VAT question entirely for employers. Blocked VAT on a company car still adds to its cost and is depreciated for Corporate Tax.
Sort the Fleet Before the Auditor Does
Exiloz reviews each vehicle's use, sorts recoverable from blocked input VAT and fixes past returns. Ask about VAT advice on company vehicles.
Frequently Asked Questions
Is VAT on a delivery van recoverable in the UAE?
Usually yes, because commercial vehicles used only for business are not available for personal use. Input VAT on it is then recoverable under the normal rules for valid tax invoices.
Does the motor vehicle rule apply to leased and rented cars?
Yes, Article 53 covers motor vehicles purchased, rented or leased for business use. If a leased car is available for personal use, each monthly lease payment then carries blocked VAT.
Who counts as any person under the vehicle rule?
The rule is not limited to employees, so directors, shareholders and their families also count. A car the owner's family can drive is available for personal use, whatever contracts say.
What if a pickup is used for site work and taken home at night?
Mixed-use vehicles are hard to defend, because being taken home makes them available for personal use. Treat them cautiously and keep clear written evidence of how each vehicle is used.
Does Cabinet Decision No. 149 of 2026 change the car rule?
No, it amends Article 53(1)(c) on staff benefits and Article 29(5) on the margin scheme purchase price. The motor vehicle block in Article 53(1)(b) is left with its existing wording.
How should wrongly claimed car VAT be corrected?
Car VAT errors of AED 10,000 or less go into the next VAT return not yet due. Larger errors need a voluntary disclosure within 20 business days of discovering them.
Does a company car count as an employee benefit for VAT?
A car available for an employee's personal use falls within the Article 53(1)(b) block for motor vehicles. The block applies whether or not the written employment contract mentions the car.
Should fuel cards be linked to specific vehicles?
Yes, linking each fuel card to one vehicle shows which running costs belong to business-only vehicles. That separation supports the input VAT claimed and makes any later FTA review simpler.
Can the blocked VAT be claimed later if a car becomes a pool car?
The block applies as long as the car is available for personal use. Once genuine pool controls start, review the position from that date and keep evidence of the change.
Can Exiloz review our company fleet for VAT?
Yes, Exiloz lists every vehicle, classifies each one against Article 53 and corrects past VAT returns where needed. We also draft pool car policies that support future input VAT claims.
Main Takeaways
UAE input VAT on vehicles available for personal use is blocked under Article 53, whoever owns them. Delivery vans, trucks and genuinely controlled pool cars usually qualify for recovery. Leased and rented cars carry the same block with each payment. Blocked cars can be resold under the profit margin scheme, and blocked VAT is depreciated as cost for Corporate Tax.
Sort the Fleet Before the Next Return
The UAE company car rule for input VAT turns on one word: available. Ownership, business mileage and the company's name on the registration card do not change the answer. Vans and properly controlled pool cars usually qualify, while staff cars taken home at night usually do not. Leases repeat any mistake every month until someone finally notices and fixes it.
List every vehicle the company owns, leases or rents, and record who uses each one. Stop claiming VAT on vehicles available for personal use and put pool car controls in writing. Then check past VAT returns for any car VAT claimed wrongly and correct it. Exiloz can review the whole fleet and fix past returns in one piece of work.
Sources & References
Accounting, Tax & Compliance Services
Accounting & Bookkeeping
Daily bookkeeping, ledger cleanup and UAE-ready financial records.
See how it works
Corporate Tax Services
Registration, return preparation and filing support for taxable persons.
See how it works
Audit Preparation Support
The schedules, reconciliations and files your auditor actually asks for.
See how it works
Payroll & WPS Support
Salary processing, WPS coordination, leave records and reporting.
See how it works
CFO & Compliance Advisory
Finance oversight and compliance planning as the business grows.
See how it works
Business Setup & Incorporation
Mainland and free zone licensing, from structure choice to trade licence.
See how it works
PRO & Document Clearing
Visas, Emirates ID, licence renewals and attestation, handled for you.
See how it works